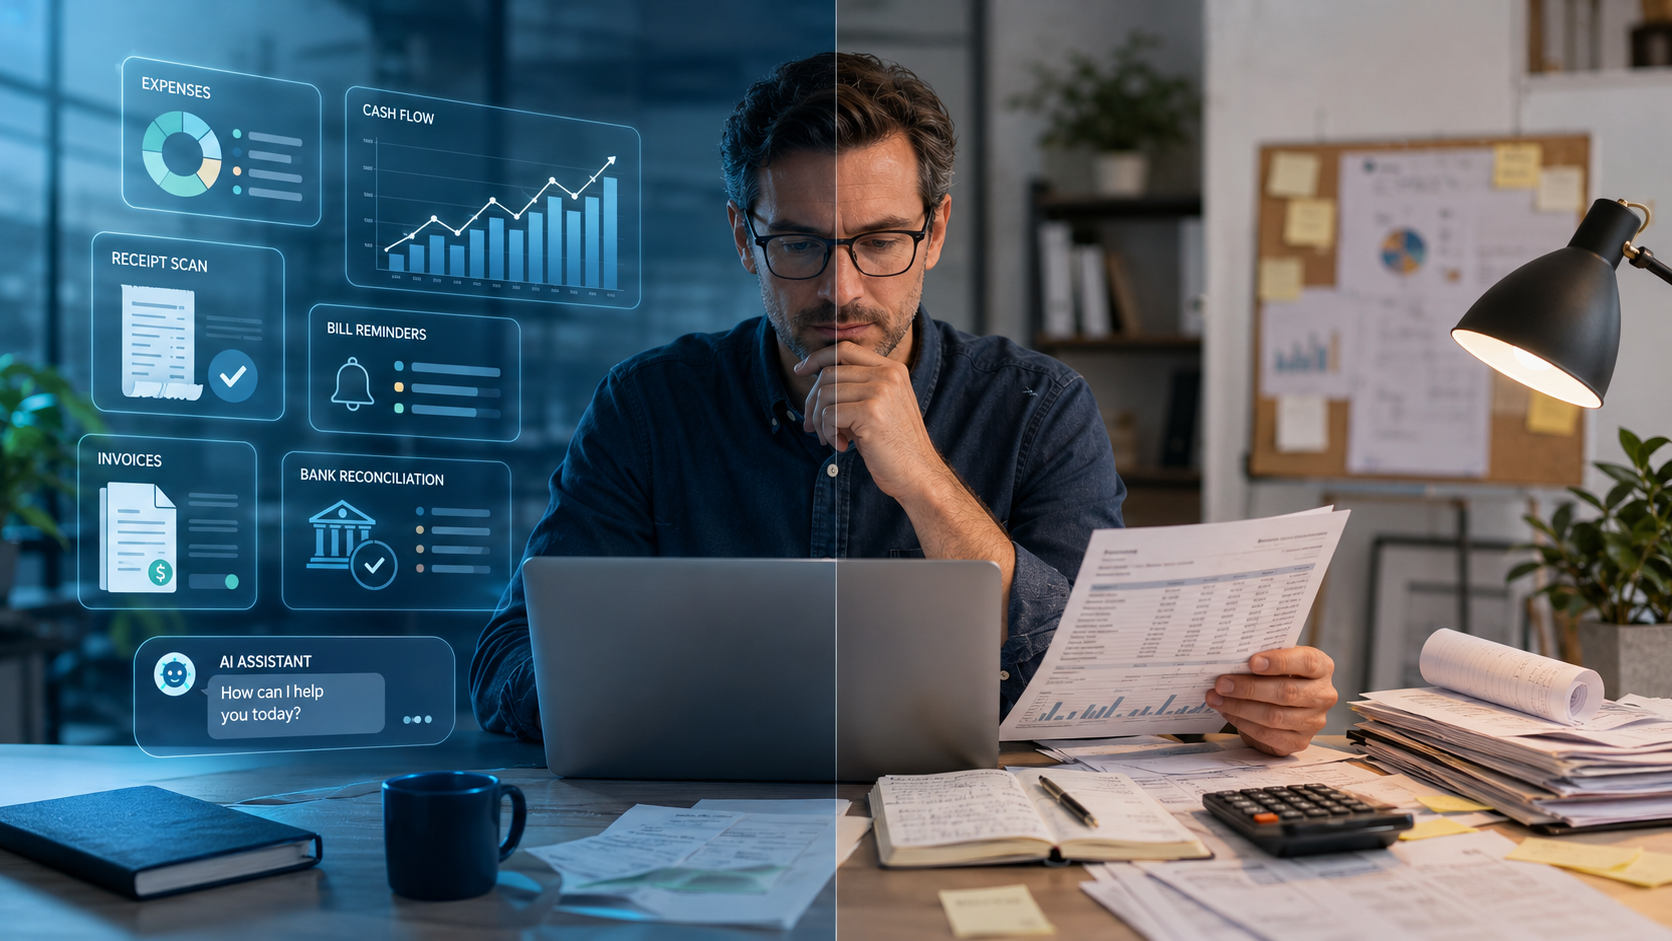
The Promise vs. the Reality
AI-powered finance tools are everywhere now. QuickBooks, FreshBooks, and newer startups like Cleo promise to automate your bookkeeping, lower your bills, and give you financial clarity—all without hiring a CFO. The pitch is compelling: let artificial intelligence handle the tedious money stuff while you focus on growing. But here's what you need to know before you hand your finances over to a chatbot.
The truth is more nuanced than the marketing suggests. AI finance tools can deliver real value for small businesses, but they're not a catch-all solution. They work best when you understand what they're actually doing—and what they're not.
Where AI Finance Tools Actually Win
The biggest win for small business owners isn't sophistication—it's removing friction. Take bill negotiation. Apps like Cleo use AI to draft negotiation emails for you. Does this represent a breakthrough in AI technology? Not really. What it does is lower the barrier to entry for something most founders avoid entirely.
Here's the practical impact: If you've been putting off contacting your internet provider about your monthly rate, an AI tool that generates that negotiation email might actually get you to take action. That's not because the AI is smarter than you—it's because it removes the psychological hurdle. The research shows these tools do help lower certain bills, but the mechanism is empowerment, not algorithmic magic.
The same principle applies to bookkeeping and expense tracking. AI automation in tools like QuickBooks and FreshBooks handles the grunt work:
- Automatically categorizing expenses from receipt photos
- Reconciling bank transactions in real-time
- Flagging unusual spending patterns
- Generating financial reports without manual data entry
For a solopreneur or small team, these time savings directly translate to hours per week you get back. That's concrete value.
The Hidden Risk: Chatbot Bias and Business Incentives
Here's where you need to stay alert. The conversational nature of AI finance chatbots can feel personal. They respond like they're invested in your financial success. They're not. They're programmed with a business objective—and every AI finance app has to be profitable to survive.
Remember Intuit Mint? A beloved app shuttered because the business model didn't work. That's the reality of consumer finance tools. Your AI finance tool isn't your friend; it's a product designed to extract value from you. This doesn't mean you shouldn't use it, but it means you should treat its advice with appropriate skepticism.
The quality of financial guidance varies dramatically between tools. Research shows that AI models deliver the most accurate and useful financial advice when they're well fine-tuned or supplemented with finance-specific training. But here's the problem: not all AI apps provide clarity on how strong their underlying models actually are.
- Legacy financial institutions (QuickBooks, FreshBooks) have years of financial data and models trained on millions of transactions. Their AI recommendations carry weight.
- Startup AI finance apps may use generic large language models without finance-specific training. Their advice could be generic—or worse, misleading.
Before you trust an AI tool's recommendations on cash flow, tax strategy, or investment decisions, ask directly: How is this model trained? What data backs it up? If the answer is vague, that's a red flag.
A Practical Framework for Small Businesses
You don't need to choose between "use AI" and "don't use AI." Instead, compartmentalize:
Use AI for Automation (High Confidence)
Let tools handle data entry, categorization, and reconciliation. This is where AI creates the most undeniable value. It's pattern-matching on structured data—exactly what AI does well.
Use AI for Nudges (Medium Confidence)
Pay attention to alerts about unusual spending or cash flow warnings. These are helpful—they flag things you might have missed. But they're not decisions. You still decide.
Verify AI Guidance (Low Confidence)
When an AI tool recommends a financial strategy—whether it's about tax optimization, pricing, or spending—treat it as a first draft, not final advice. Run it by your accountant or a human financial advisor. This is especially true for decisions with tax implications.
Questions to Ask Before Adopting an AI Finance Tool
- Does it integrate with my existing accounting system? Fragmented tools create more work, not less.
- How is the underlying AI model trained? Generic or finance-specific?
- What's the pricing model? Is the company profitable, or are they burning investor cash? (Mint's shutdown is instructive here.)
- How transparent is it about limitations? A tool that admits what it can't do is more trustworthy than one that oversells capabilities.
- Is there a human escalation path? For important decisions, can you talk to someone?
The Bottom Line for Founders
AI finance tools are worth using—specifically for automation and efficiency. QuickBooks with AI-powered categorization will save you hours per month. FreshBooks' automated invoicing and expense tracking eliminate busywork. Cleo's bill negotiation prompt might actually get you to renegotiate your subscriptions.
But don't mistake convenience for wisdom. These tools excel at making tedious financial tasks frictionless. They're weaker at making complex financial decisions. And they're built on business models that aren't always aligned with your interests.
The best approach: Use AI finance tools as your efficient automation layer and reporting engine. For strategy and judgment calls, keep a human in the loop. That combination gives you the efficiency gains of AI without the blind spot of over-trusting an algorithm.